
Credit scores are used to help make important financial decisions—but credit scoring does not work the same way everywhere in the world.
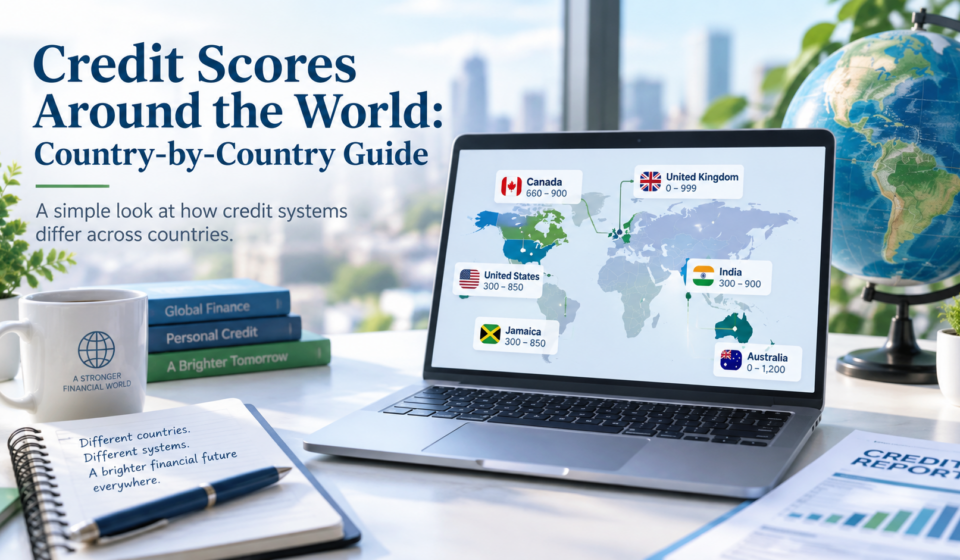
A consumer in the United States may see a credit score between 300 and 850. Someone in Canada may see a score on a 300-to-900 scale. Australia uses still different ranges, while the United Kingdom has multiple credit reference agencies with their own scoring systems.
So, is there an international credit score?
No. There is no single universal credit score used worldwide.
Different countries have their own credit bureaus, credit-reporting laws, scoring systems, data sources, and lending practices. Even within one country, consumers may have different scores depending on the credit bureau or scoring model.
Despite those differences, most systems share a common goal: helping lenders assess creditworthiness, or the risk involved in lending money to a borrower.
This guide explains how credit scores work around the world, compares several major credit systems, and answers an important question for anyone moving abroad: Does your credit history follow you to another country?
What Is Creditworthiness?
Creditworthiness describes how likely a borrower appears to repay money according to the agreed terms.
Banks, credit bureaus, and other lenders may evaluate information such as:
- Payment history
- Outstanding debt
- Available credit
- Length of credit history
- Recent credit applications
- Defaults or collections
- Insolvency or bankruptcy information, where applicable
- Types of credit accounts
- Previous borrowing behavior
However, not every country—or every scoring model—uses these factors in exactly the same way.
A credit score may summarize some of this information into a number, but creditworthiness is broader than a credit score.
A lender may also consider income, employment, affordability, existing financial obligations, assets, and its own underwriting policies.
Is There a Global Credit Score?
No.
There is no universal global credit score that determines your creditworthiness everywhere you go.
Credit-reporting systems generally operate within individual countries or jurisdictions.
That means:
A 750 credit score in one country is not necessarily equivalent to a 750 somewhere else.
Countries may have:
- Different scoring ranges
- Different credit bureaus
- Different reporting requirements
- Different consumer protection laws
- Different information available to lenders
- Different methods for calculating risk
- Different lending standards
Even countries using similar numerical ranges may calculate and interpret their scores differently.
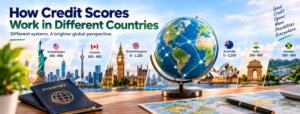
Credit Score Ranges by Country: Quick Comparison
| Country | Typical Score/System | Important Difference |
| United States | Many scores use 300–850 | Multiple bureaus, models, and score versions |
| Canada | Generally 300–900 | Equifax and TransUnion are the two main bureaus |
| United Kingdom | Varies by credit reference agency | No single consumer score used by every lender |
| Australia | 0–1,000 or 0–1,200 | Scale depends on the credit reporting agency |
| Germany | SCHUFA’s newer score uses 100–999 | Uses its own defined scoring criteria |
| India | Commonly 300–900 | Multiple regulated Credit Information Companies |
| China | Financial credit-reporting system | Should not be confused with one universal “social credit score” |
Important: These systems and score ranges can change. Credit bureaus and lenders may also use different models within the same country.
How Credit Scores Work in Different Countries
United States: Multiple Credit Scores, Often From 300 to 850
The United States has one of the world’s most recognizable consumer credit systems.
The three major nationwide credit reporting companies are:
- Equifax
- Experian
- TransUnion
These companies maintain credit reports containing information about consumers’ borrowing and repayment histories.
Many commonly used U.S. credit scores range from 300 to 850, with higher scores generally indicating lower predicted credit risk.
Two well-known credit-scoring brands are FICO® and VantageScore®.
However, Americans don’t have just one credit score.
A consumer’s scores can vary depending on:
- The scoring model
- The version of the scoring model
- Which credit bureau supplied the information
- When the score was calculated
- The type of lending decision
Common credit-scoring factors can include payment history, outstanding debt, revolving-credit utilization, account age, recent credit activity, and the types of accounts being managed.
A higher score may help a borrower qualify for more favorable financing, but even an excellent credit score does not guarantee approval.
Lenders can also evaluate income, existing debt, affordability, down payment, and other underwriting factors.
Canada: Credit Scores Generally Range From 300 to 900
Canada’s credit system shares several characteristics with the United States, but the scoring range is different.
Canadian credit scores generally range from 300 to 900, with higher scores typically representing stronger creditworthiness.
Canada’s two main credit bureaus are:
- Equifax
- TransUnion
Information that may affect Canadian credit scores includes:
- Payment history
- Outstanding debt
- Credit limits
- Length of credit history
- Types of credit
- Collection activity
- Recent credit applications
The score or information supplied by one bureau may differ from another because the bureaus may not have exactly the same information or use identical scoring calculations.
Does Your Foreign Credit History Transfer to Canada?
Not automatically.
Canada’s credit bureaus primarily collect information about credit activity reported within Canada.
Someone who moves to Canada after maintaining excellent credit elsewhere may therefore need to establish a Canadian credit history.
A lender may sometimes consider foreign financial or credit information separately, but borrowers should not assume an overseas credit score will automatically become a Canadian score.
United Kingdom: Different Agencies Use Different Credit Scores
The United Kingdom provides a particularly good example of why credit scores shouldn’t be compared internationally without context.
The UK does not have one official consumer credit score used by every lender.
Instead, credit reference agencies maintain credit information and may provide consumers with their own scores.
Different agencies can use different ranges.
For example, Experian UK’s newer consumer scoring system uses a 0-to-1,250 scale.
But the score consumers see isn’t necessarily the score—or exact decision-making system—a lender uses.
UK lenders may evaluate information including:
- Payment history
- Outstanding debt
- Available credit
- Recent applications
- Defaults
- Relevant public-record information
- Income and expenditure
- Their own relationship with the applicant
- Internal lending criteria
Two lenders can therefore reach different decisions about the same applicant.
If someone says, “My UK credit score is 800,” the number alone doesn’t provide enough information. You also need to know which credit reference agency produced it and what scoring range it uses.
Australia: Credit Scores May Reach 1,000 or 1,200
Australia uses credit reports and credit scores to help assess consumer credit risk.
Depending on the credit reporting agency, an Australian credit score may range from 0 to either 1,000 or 1,200.
Higher scores generally indicate lower predicted credit risk.
Factors that may influence Australian credit assessments include:
- Repayment history
- Amounts borrowed
- Credit accounts
- Credit applications
- Defaults
- Certain insolvency information
Australia illustrates another important point:
Credit score ranges can differ even within the same country.
Consumers should therefore pay attention not only to the number but also to which credit reporting agency produced the score and the range it uses.
Germany: Understanding the SCHUFA Score
Germany is well known for SCHUFA, a major credit information organization used when assessing creditworthiness.
SCHUFA’s newer scoring system uses a 100-to-999 point scale and evaluates a defined set of criteria relating to a consumer’s credit profile.
These criteria can include information connected with:
- Payment problems
- Banking relationships
- Credit cards
- Credit inquiries
- Installment loans
- Loan status
- Mortgages
- Other relevant credit information
An important distinction is that SCHUFA does not make the final lending or contractual decision.
A bank or other company can combine SCHUFA information with its own information and requirements when deciding whether to approve a customer.
India: CIBIL and the 300-to-900 Scale
India has multiple Credit Information Companies operating within its regulated credit-reporting framework.
These include organizations such as:
- TransUnion CIBIL
- Experian
- Equifax
- CRIF High Mark
One of India’s best-known consumer credit scores is the CIBIL Score.
CIBIL scores generally range from 300 to 900, with higher scores indicating lower predicted credit risk.
Credit information can include factors related to:
- Payment behavior
- Outstanding balances
- Credit utilization
- Account history
- Types of credit
- Recent inquiries
- Historical borrowing patterns
Banks and other lenders can use this information alongside additional financial information when evaluating an application.
Again, a score is a risk indicator—not an automatic approval or rejection.
China: Financial Credit Reporting Is Not One Universal “Social Credit Score”
China’s system requires additional explanation because financial credit reporting is often confused with the country’s broader social credit policies.
The People’s Bank of China’s Credit Reference Center operates financial credit-reporting infrastructure that contains information reflecting the credit status of individuals and businesses.
This financial credit system should not simply be described as a nationwide FICO-style “social credit score.”
China also has a broader social-credit framework involving regulatory records, public credit information, compliance, incentives, restrictions, and other mechanisms across different sectors.
Those systems are more complicated than the popular idea that every Chinese citizen receives one government-generated number controlling every aspect of daily life.
For consumers comparing international credit systems, the key distinction is:
China’s financial credit reporting and its broader social-credit framework are not one universal consumer credit score.
Example: The Same Borrower in Different Countries
Imagine a fictional borrower named Maya.
Maya has:
- Never missed a loan or credit-card payment
- Maintained credit accounts for five years
- The equivalent of a $10,000 credit-card limit
- A balance equivalent to $2,000
- One installment loan
- Only one recent application for additional credit
Her revolving credit utilization would be:
$2,000 ÷ $10,000 × 100 = 20%
Now imagine Maya living in several different countries.
United States
Her history of on-time payments, established accounts, and relatively low revolving utilization could generally contribute positively to her credit profile.
Canada
Similar behaviors—including timely payments, debt levels, account age, and balances relative to credit limits—could influence her Canadian credit profile, but her resulting score would generally be expressed on a different scale.
Australia
Her repayment history, borrowing level, and credit applications could affect a score that may run to either 1,000 or 1,200, depending on the reporting agency.
Germany
SCHUFA would use its own methodology and criteria to evaluate relevant information and produce its score.
India
A CIBIL model could evaluate payment behavior, utilization, account information, inquiries, and other credit history and express the resulting risk assessment on a 300-to-900 scale.
Maya’s responsible financial behavior can remain valuable regardless of where she lives.
But there is no reliable formula for converting her credit score from one country’s system into another country’s score.
What Do Credit Systems Around the World Have in Common?
Although the details vary considerably, several themes appear across many credit systems.
Paying On Time Matters
A record of meeting payment obligations can demonstrate responsible borrowing behavior.
Repeated late payments, defaults, or collections can indicate increased risk.
Debt Matters
Lenders want to know how much a borrower already owes and whether additional debt appears manageable.
Some scoring systems also consider the relationship between revolving balances and available credit.
Credit History Matters
An established record of successfully managing financial obligations can provide more information about a borrower’s behavior over time.
Credit Applications Can Matter
Repeatedly applying for new loans or other credit products over a short period may affect credit assessments in some systems.
A Credit Score Is Only Part of the Decision
A lender may consider much more than a credit score.
Depending on the country and financial product, additional factors may include:
- Income
- Employment
- Affordability
- Existing debt
- Monthly expenses
- Assets
- Collateral
- Loan amount
- Loan type
- Internal lender risk policies
That means a high credit score doesn’t guarantee approval, just as a lower score doesn’t necessarily make borrowing impossible.
Does Your Credit Score Follow You to Another Country?
Usually, you should not assume your credit score will automatically follow you when you move abroad.
Credit-reporting systems operate under different national laws, databases, reporting networks, and financial institutions.
For example, someone could maintain excellent credit in the United States for 10 years and then move to another country where the local credit bureaus don’t automatically have access to that history.
The person’s responsible financial habits haven’t disappeared—but the local system may have little or no information from which to generate a local credit profile.
This can be particularly important for:
- Immigrants
- International students
- Expatriates
- People relocating for work
- Returning residents
Does Your Credit History Transfer Between Countries?
Generally, credit history doesn’t automatically transfer between national credit-reporting systems.
However, that doesn’t necessarily mean your previous financial history is useless.
Depending on the country and lender, you may be able to provide:
- Foreign credit reports
- Bank statements
- Proof of income
- Employment records
- References from financial institutions
- Other evidence of financial stability
Some financial institutions and specialized services may also offer products designed for newcomers or people with international financial histories.
Policies vary, so always check with the lender and local credit bureaus.
How to Build Credit After Moving to Another Country
Moving internationally may mean establishing a local credit history from the beginning.
Here are several steps that can help.
1. Learn How the Local Credit System Works
Identify the credit bureaus, financial regulators, and consumer protection agencies operating in your new country.
Don’t assume advice written for another country applies locally.
2. Check Whether You Have a Local Credit Report
Find out whether local credit bureaus already have information associated with you and how you can access it.
3. Pay Financial Obligations on Time
Consistent repayment behavior can help establish a positive local financial history where those payments are reported.
4. Use Credit Responsibly
If you obtain a credit card or loan, borrow only what you can reasonably afford to repay.
5. Avoid Applying for Too Much Credit at Once
Submitting many applications shortly after relocating may not help establish the type of profile you want.
6. Review Your Credit Information for Errors
Once you have an established credit report, review it periodically and follow the local dispute process if you identify inaccurate information.
Frequently Asked Questions About International Credit Scores
Is there an international credit score?
No. There is no single international credit score used by lenders worldwide. Credit systems are generally country-specific.
Which countries use credit scores?
Many countries use some form of credit reporting, credit scoring, credit rating, or lender risk assessment, but the exact systems vary significantly. The United States, Canada, UK, Australia, Germany, and India are examples of countries with established consumer credit-reporting systems.
Does my U.S. credit score work in another country?
Usually not directly. U.S. credit scores are calculated using information within U.S. credit-reporting systems. A foreign lender may have a separate process for considering overseas financial information.
Does your credit score reset when you move countries?
“Reset” isn’t quite the right term. Your existing score doesn’t necessarily disappear, but the new country’s credit-reporting system may not automatically have access to your previous history. You may therefore need to establish a new local credit profile.
Can you transfer a credit score from one country to another?
Generally, there isn’t a simple process for converting or transferring one country’s credit score into another country’s score. Some lenders may consider foreign credit information separately.
Is a 750 credit score good in every country?
No. A score of 750 cannot be interpreted without knowing the country, credit bureau, scoring model, and overall scoring range.
Is 850 the highest credit score worldwide?
No. Although 850 is the maximum for several widely known U.S. scoring models, other countries and credit agencies use different maximum scores.
Can I build credit after moving abroad?
Yes. Depending on the country’s system, you may be able to establish credit through locally reported accounts and consistent repayment behavior. The exact options vary by country.
Why are international credit scores different?
Credit systems use different laws, data sources, scoring models, credit bureaus, ranges, and lender requirements. There is no global standard requiring every country to calculate credit risk in the same way.
Final Thoughts
Credit scores around the world cannot be compared using numbers alone.
A 750 in the United States, Canada, India, or Germany does not necessarily mean the same thing because each system can use different ranges, information, models, and lending practices.
The better approach is to understand the credit system where you live and focus on the behaviors that commonly demonstrate responsible financial management:
- Pay financial obligations on time.
- Manage debt carefully.
- Avoid borrowing more than you can reasonably repay.
- Apply for new credit thoughtfully.
- Review your credit information for inaccuracies.
- Learn your rights under local credit-reporting laws.
And if you’re moving internationally, don’t assume years of excellent credit will automatically transfer into your new country’s system. Research the local credit bureaus and financial institutions before you move so you know what documentation you may need and how to begin establishing a local credit history.
Credit may be a global concept, but credit scores are local.
Understanding that difference can help you make smarter borrowing decisions wherever life takes you.
Disclaimer: This article is for general educational and informational purposes only. It does not constitute individualized financial, legal, credit, or lending advice. Credit-reporting laws, scoring models, score ranges, and lender policies vary by country and can change over time.