
Your credit score can affect some of your biggest financial decisions—from getting your first credit card to financing a car or buying a home.
But have you ever wondered how your credit score is actually calculated?
Credit scores aren’t randomly assigned. Credit-scoring companies use mathematical models that analyze information contained in your credit reports to estimate the likelihood that you’ll repay borrowed money as agreed.
The exact formulas can be complex, and there’s another important detail:
You don’t have just one credit score.
Different lenders may use different scoring models, versions of those models, or information from different credit bureaus. As a result, the score you see in a banking app may not be identical to the score a lender uses.
While several scoring models exist, this guide focuses primarily on the FICO® Score, one of the best-known credit-scoring systems in the United States.
How Is Your Credit Score Calculated?
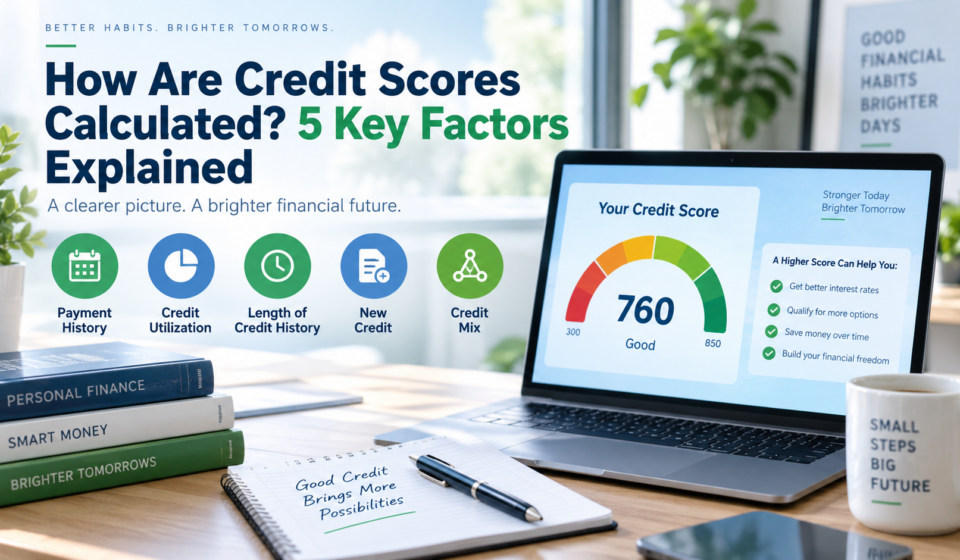
For a typical FICO Score, information from your credit report is grouped into five major categories:
| Credit Score Factor | Approximate Weight |
| Payment History | 35% |
| Amounts Owed | 30% |
| Length of Credit History | 15% |
| New Credit | 10% |
| Credit Mix | 10% |
At first glance, this might look like a simple formula.
It isn’t.
These percentages describe the approximate importance of each category for the general population. They don’t mean you can take five numbers, multiply each by its percentage, add them together, and calculate your FICO Score yourself.
The importance of individual factors can vary depending on the information in your credit report.
Let’s look at each category.
The 5 Main Factors That Affect Your FICO Score
1. Payment History — About 35%
Payment history is generally the largest factor in a typical FICO Score.
Credit-scoring models look at how you’ve handled your payment obligations in the past.
Your credit report may show whether payments were made as agreed and whether you’ve experienced serious payment problems.
Negative information may include:
- Late payments
- Missed payments
- Accounts sent to collections
- Defaults
- Certain public-record information such as bankruptcy
Consistently making required payments on time, on the other hand, can help establish a positive payment history.
Payment History Example
Suppose Maria has had a credit card for three years.
Every month, she makes at least the required payment by the due date and has never missed a payment.
That history of paying as agreed can contribute positively to her credit profile.
Key takeaway: If you’re trying to build healthy credit, paying your obligations on time is one of the most important habits to establish.
2. Amounts Owed — About 30%
The amount you owe is another major component of a typical FICO Score.
But this category involves more than simply asking:
“How much debt do you have?”
Scoring models can evaluate your debt in relation to your accounts and available credit.
For revolving accounts such as credit cards, one particularly important concept is credit utilization.
What Is Credit Utilization?
Your credit utilization ratio measures how much of your available revolving credit you’re currently using.
The basic calculation is:
Credit utilization = Credit card balance ÷ Credit limit × 100
Credit Utilization Example
Suppose your credit card has:
- Credit limit: $5,000
- Reported balance: $1,000
Your utilization would be:
$1,000 ÷ $5,000 × 100 = 20%
You’re using 20% of the available credit on that account.
Generally, lower revolving utilization can be more favorable to a credit score than using a large percentage of your available credit, assuming the rest of the credit profile remains the same.
Is 30% Credit Utilization a Rule?
You’ve probably heard that you should always keep credit utilization below 30%.
It’s better to think of 30% as a commonly cited guideline rather than a magical cutoff.
Your score doesn’t suddenly become “good” at 29% and “bad” at 31%.
Lower utilization can generally be more favorable, but your score depends on your entire credit profile.
You also do not need to carry credit-card debt or pay interest to build a good credit score.
3. Length of Credit History — About 15%
Credit-scoring models also consider how long you’ve been managing credit.
FICO may consider information such as:
- The age of your oldest credit account
- The age of your newest account
- The average age of your accounts
- How long particular accounts have been established
- How long it has been since you used certain accounts
Why does account age matter?
A longer history gives a scoring model more information about how you’ve managed credit over time.
For example, someone who has responsibly managed an account for eight years provides more historical information than someone who opened their first credit account two months ago.
However, having a relatively short credit history doesn’t automatically mean you can’t have good credit.
Key takeaway: Building credit takes time, which is one reason maintaining older, responsibly managed accounts can sometimes be beneficial.
4. New Credit — About 10%
Applying for and opening new credit can also affect your FICO Score.
When you formally apply for a loan or credit card, a lender may review your credit report. This can result in what’s known as a hard inquiry.
A single hard inquiry isn’t necessarily a major problem.
However, opening several accounts or repeatedly seeking new credit within a short period can represent increased risk—particularly for someone with a relatively short credit history.
Does Every Credit Check Hurt Your Score?
No.
Checking your own credit is generally considered a soft inquiry and doesn’t affect your FICO Score.
Hard inquiries associated with applications for new credit can potentially affect a score.
Also, certain scoring models recognize that consumers may shop around for rates on particular types of loans. Depending on the scoring model and timing, multiple qualifying inquiries made while rate shopping may be treated differently than several unrelated applications.
Key takeaway: Don’t be afraid to use credit when you genuinely need it, but avoid applying for unnecessary accounts simply because they’re available.
5. Credit Mix — About 10%
Credit mix refers to the different types of credit accounts you’ve managed.
Credit accounts can generally be divided into categories such as revolving and installment credit.
Examples include:
- Credit cards
- Auto loans
- Mortgages
- Student loans
- Personal loans
- Retail accounts
- Other installment loans
Successfully managing different types of accounts can provide additional information about how you handle credit.
But there’s an important warning:
Don’t take out a loan or open an unnecessary account solely to improve your credit mix.
Credit mix accounts for a relatively small portion of a typical FICO Score, and taking on unnecessary debt can create more financial risk than potential credit-score benefit.
Credit Score Calculation Example
Let’s put these concepts together with a fictional borrower named Jordan.
Jordan has:
- A credit card open for five years
- $10,000 in total available revolving credit
- $1,500 in reported credit-card balances
- An auto loan with on-time payments
- No missed payments
- No recent collection accounts
- One recent credit application
First, let’s calculate Jordan’s overall revolving utilization:
$1,500 ÷ $10,000 × 100 = 15%
Jordan therefore has 15% credit utilization based on this simplified example.
Jordan also has several characteristics that could support a stronger credit profile:
Payment history: No missed payments.
Amounts owed: Relatively low revolving utilization.
Credit history: An account has been established for five years.
New credit: Only one recent application.
Credit mix: Experience managing both revolving and installment credit.
So what is Jordan’s exact FICO Score?
We don’t know—and that’s an important point.
You cannot accurately calculate Jordan’s FICO Score by simply assigning points to each category and multiplying them by 35%, 30%, 15%, 10%, and 10%.
Those percentages aren’t a public point-by-point scoring formula.
FICO’s models evaluate the information in a person’s overall credit report, and the relative importance of specific information can differ depending on the credit profile.
Two people could both have 15% credit utilization and still have substantially different scores because their payment histories, account ages, credit inquiries, and other credit information differ.
What Affects Your Credit Score the Most?
For a typical FICO Score, payment history has the largest approximate weighting at 35%, followed by amounts owed at approximately 30%.
Together, these categories represent a substantial portion of the factors used in a typical FICO Score.
That means two of the most important areas to focus on are:
- Paying your obligations on time.
- Managing your credit-card balances and overall debt responsibly.
However, you shouldn’t ignore the remaining categories.
A credit score evaluates your overall credit profile, and one consumer’s situation can differ considerably from another’s.
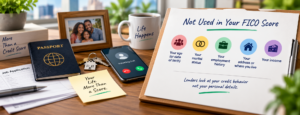
What Information Is Not Used to Calculate Your FICO Score?
Your FICO Score is based on information contained in your credit report.
Some information that lenders may care about isn’t part of the FICO Score calculation itself.
For example, your income is not part of your FICO Score.
Other information not considered by FICO includes certain personal characteristics prohibited or excluded from its scoring process.
This creates an important distinction:
Your credit score and a lender’s approval decision are not the same thing.
A lender may separately consider factors such as:
- Income
- Employment
- Monthly debt obligations
- Debt-to-income ratio
- Down payment
- Assets
- Loan amount
- Type of financing
- Its own underwriting requirements
You could therefore have an excellent credit score and still not qualify for a particular loan if you don’t meet the lender’s other requirements.
Why Do You Have Different Credit Scores?
Seeing different scores can be confusing, but it doesn’t necessarily mean something is wrong.
You can have multiple credit scores because of differences in:
- Scoring models: FICO and VantageScore use different models.
- Model versions: Multiple generations and versions of scoring models exist.
- Credit bureaus: Equifax, Experian, and TransUnion may not contain identical information at the same time.
- Timing: Creditors report updated balances and account information at different times.
- Loan type: Some lenders may use scores designed for particular types of lending.
For example, the score displayed by a free credit-monitoring service may not be the exact scoring model an auto lender or mortgage lender uses.
Rather than assuming one score is “correct” and another is “wrong,” check which scoring model and credit bureau produced each score.
What Can Make Your Credit Score Go Down?
Several changes to your credit report can potentially lower your score, depending on your overall profile and scoring model.
Examples may include:
- Missing a payment
- Making a payment late enough for it to be reported
- Increasing revolving-credit balances
- Using a large percentage of available credit
- Opening several accounts within a short period
- Applying for multiple new credit accounts
- Having an account sent to collections
- Experiencing other serious negative credit events
The impact isn’t identical for everyone.
A particular change might have a larger effect on one person’s score than another’s because their credit histories are different.
How Can You Improve Your Credit Score?
There is no legitimate trick that guarantees a specific number of points overnight.
Instead, focus on improving the underlying information used to generate your credit scores.
Pay Your Bills on Time
Payment history is highly influential in typical FICO Scores.
Set reminders or automatic payments if they help you avoid missing due dates.
Reduce Credit-Card Balances
Paying down revolving balances can reduce your credit utilization.
Lower utilization can generally support a stronger credit profile.
Apply for Credit Selectively
Don’t open accounts you don’t need simply to try to improve your score.
Maintain Established Accounts When Appropriate
Older accounts can contribute to the length of your credit history.
That doesn’t mean you should never close an account—particularly one with fees or other disadvantages—but consider the possible credit implications before doing so.
Review Your Credit Reports
Credit scores are generated from information contained in your credit reports.
Reviewing those reports can help you identify:
- Accounts you don’t recognize
- Incorrect late payments
- Incorrect balances
- Duplicate information
- Other possible reporting errors
If you find inaccurate information, follow the appropriate dispute process.
Frequently Asked Questions About How Credit Scores Are Calculated
How is a credit score calculated?
Credit-scoring companies use mathematical models to analyze information in your credit reports. A typical FICO Score considers payment history, amounts owed, length of credit history, new credit, and credit mix.
What are the 5 factors that affect a FICO Score?
For a typical FICO Score, the five major categories and approximate weights are:
- Payment history: 35%
- Amounts owed: 30%
- Length of credit history: 15%
- New credit: 10%
- Credit mix: 10%
These percentages indicate approximate category importance and aren’t a formula consumers can use to calculate an exact score.
What affects your credit score the most?
Payment history generally carries the largest approximate weighting in a typical FICO Score at 35%, followed by amounts owed at approximately 30%.
Does income affect your credit score?
Your income is not included in the calculation of a FICO Score. However, lenders may consider income separately when deciding whether you can afford a loan.
Does checking your credit score lower it?
Checking your own credit score or credit report generally involves a soft inquiry and doesn’t lower your FICO Score.
Does carrying a credit-card balance improve your credit score?
You don’t need to carry a balance or pay interest to build credit. Responsible account management and on-time payments are what matter.
Is 30% credit utilization good?
Keeping utilization below 30% is a widely cited guideline, but 30% isn’t a hard scoring threshold. Generally, lower utilization can be more favorable, depending on the rest of your credit profile.
Can I calculate my exact FICO Score myself?
No. FICO’s exact scoring algorithms are proprietary. The commonly cited 35%, 30%, 15%, 10%, and 10% figures describe the approximate importance of five categories, not a public formula for calculating your exact score.
How often is a credit score calculated?
A credit score can be calculated when it is requested using the information available in your credit report at that time. As the underlying information changes, the resulting score may also change.
Final Thoughts
So, how are credit scores calculated?
Credit-scoring models analyze information from your credit reports to estimate how likely you are to repay borrowed money as agreed.
For a typical FICO Score, the five major categories are:
| Factor | Approximate Weight |
| Payment History | 35% |
| Amounts Owed | 30% |
| Length of Credit History | 15% |
| New Credit | 10% |
| Credit Mix | 10% |
But remember: these percentages aren’t an exact scoring formula.
Your score depends on your complete credit profile, the scoring model being used, the information available from the credit bureau, and when the score is calculated.
Rather than trying to manipulate individual points, focus on the financial habits behind your score: pay your obligations on time, keep revolving balances manageable, apply for credit thoughtfully, maintain established accounts when appropriate, and regularly review your credit reports.
Those habits can help you build a healthier credit profile over time—and that’s ultimately more valuable than chasing a particular three-digit number.
Disclaimer: This article is for general educational and informational purposes only and does not constitute individualized financial, credit, or lending advice. Credit-scoring models and lender requirements vary.