
Whether you’re applying for a mortgage in the United States, financing a vehicle in Canada, or seeking a personal loan in Australia, lenders all ask a similar question:
How likely is this person to repay the money they borrow?
The answer often comes from reviewing your credit history, credit report, credit score, or a combination of these factors.
While the concept of credit exists in many countries, there is no universal credit score. Every country has its own credit reporting laws, scoring models, financial regulations, and lending practices. That means a score considered excellent in one country may have little meaning in another.
In this guide, we’ll explain how credit scores work around the world, compare major credit systems, and highlight the financial habits that can help build strong credit no matter where you live.
What Is a Credit Score?
A credit score is a numerical estimate of how likely a borrower is to repay borrowed money according to the agreed terms.
Credit scores are calculated using information found in a person’s credit report. Although the exact formula varies by country and credit bureau, common factors include:
- Payment history
- Outstanding debt
- Credit utilization (where applicable)
- Length of credit history
- Types of credit accounts
- Recent credit applications
- Defaults, collections, or other serious repayment issues
Generally, a higher credit score indicates lower lending risk, while a lower score may indicate greater risk.
Important: A credit score is only one part of a lending decision. Financial institutions may also review your income, employment, assets, existing debts, and other financial information.
Credit Score vs. Credit Report
These two terms are closely related but serve different purposes.
| Credit Report | Credit Score |
| A detailed record of your borrowing history | A numerical summary of your creditworthiness |
| Includes loans, credit cards, payment history, balances, and inquiries | Calculated using information from your credit report |
| Maintained by credit reporting agencies | Generated using credit scoring models |
Think of it this way:
Your credit report tells your financial story.
Your credit score summarizes that story into a number.
Lenders may review one or both before making lending decisions.
How Credit Scores Work Around the World
Although every country has its own credit reporting system, most lenders look for similar financial behaviors—such as paying bills on time and managing debt responsibly.
United States
The United States has one of the world’s most established consumer credit systems.
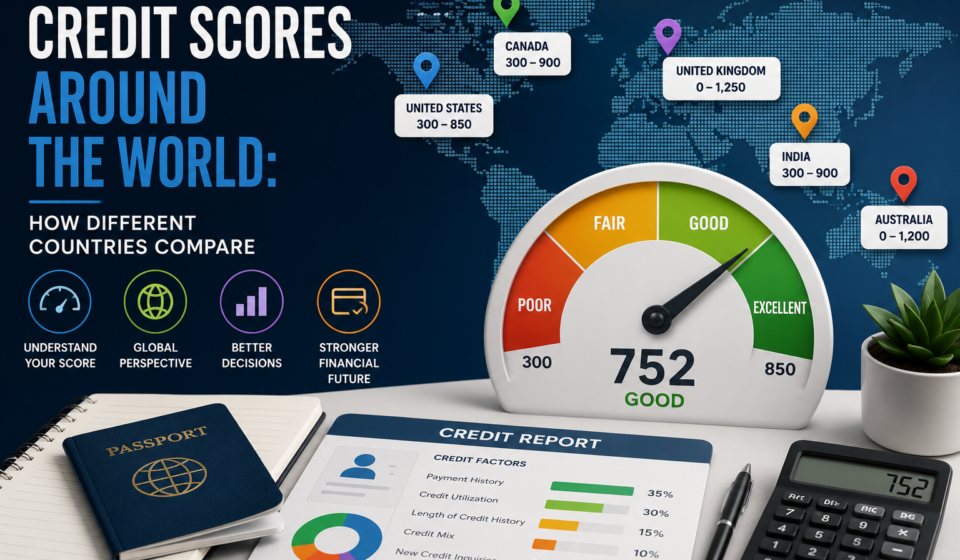
Consumers may have multiple credit scores because different scoring models and credit reporting agencies are used. Many widely used scoring models range from 300 to 850.
Credit scores can influence eligibility for:
- Credit cards
- Auto loans
- Mortgages
- Personal loans
- Student loans
Lenders may also consider income, debt-to-income ratio, employment history, and other financial factors when evaluating applications.
Canada
Canada uses a credit reporting system similar to that of the United States.
The country’s major credit bureaus maintain credit reports and generate credit scores that help lenders evaluate repayment risk.
Canadian consumers are encouraged to review their credit reports regularly to identify errors or potential fraud.
United Kingdom
The United Kingdom uses credit reference agencies rather than a single national credit score.
These agencies collect credit information and provide reports that lenders may review during the application process.
One important difference is that lenders often rely heavily on their own internal lending criteria. A strong score from a credit reference agency does not automatically guarantee loan approval.
Australia
Australia operates under a comprehensive credit reporting system.
Credit reporting agencies may use different scoring ranges, with some scores reaching 1,000 or 1,200, depending on the provider.
Information commonly considered includes:
- Repayment history
- Outstanding borrowing
- Credit inquiries
- Credit account history
Because scoring models differ, Australian credit scores should not be directly compared with scores from other countries.
India
India’s credit reporting system is regulated by the Reserve Bank of India (RBI).
Credit Information Companies generate consumer credit scores using a standardized 300 to 900 range.
Banks and financial institutions use these scores, along with other financial information, when evaluating loan applications.
Jamaica
Jamaica has a regulated credit reporting framework overseen by the Bank of Jamaica under the Credit Reporting Act.
Licensed credit bureaus collect and maintain eligible credit information, allowing lenders to assess a borrower’s creditworthiness.
Credit scores may be generated using credit bureau information to estimate the likelihood that a borrower will repay as agreed.

Credit Score Comparison by Country
| Country | Typical Credit Score range | Primary Credit System |
| United States | 300–850 | Multiple scoring models |
| Canada | Varies by bureau/model | Credit bureaus |
| United Kingdom | Varies by agency | Credit reference agencies |
| Australia | Up to 1,000 or 1,200 (varies) | Credit reporting agencies |
| India | 300–900 | Credit Information Companies |
| Jamaica | Varies by bureau/model | Licensed credit bureaus |
ranges vary depending on the scoring model and reporting agency.
Example: Why Credit Scores Can’t Be Compared Internationally
Imagine three people applying for loans.
Sarah lives in the United States and has a score of 760.
David lives in Australia and has a score of 890 using an Australian scoring model.
Priya lives in India and has a score of 790 on India’s 300–900 scale.
Although all three scores appear different, they cannot be compared directly because each country uses different scoring systems and evaluation methods.
What matters most is that each borrower demonstrates responsible financial behavior according to the standards used in their own country.
Why Does Good Credit Matter?
Regardless of where you live, maintaining a positive credit history may help you:
- Qualify for loans
- Obtain a credit card
- Receive more competitive interest rates
- Access higher borrowing limits
- Secure more favorable loan terms
- Demonstrate financial responsibility to lenders
Remember, a strong credit score does not guarantee approval. Lenders often evaluate additional factors before making a lending decision.
How to Build Healthy Credit
While credit reporting systems vary across countries, many of the same financial habits contribute to good credit.
1. Pay Your Bills on Time
Consistently making payments by their due dates helps build a positive repayment history.
2. Borrow Responsibly
Only borrow what you can comfortably afford to repay. High levels of debt may increase financial risk and affect future borrowing opportunities.
3. Limit Unnecessary Credit Applications
Applying for multiple loans or credit cards within a short period may affect your credit profile in many countries.
Only apply for credit when you genuinely need it.
4. Review Your Credit Report Regularly
Checking your credit report allows you to:
- Identify reporting errors
- Detect potential fraud
- Verify account information
- Monitor your financial progress
Many consumer protection agencies recommend reviewing your credit report regularly.
5. Understand Your Country’s Credit System
Credit laws, scoring models, and consumer rights differ significantly around the world.
Before making important financial decisions, learn how credit works in your country and consult official consumer resources when needed.
Does Everyone Have a Credit Score?
No.
Not every country relies on a numerical credit score.
Some financial systems place greater emphasis on:
- Income
- Existing debt
- Employment
- Banking history
- Affordability assessments
- Internal lender evaluations
For example, throughout the European Union, lenders are generally required to assess a borrower’s creditworthiness before approving credit. However, this does not mean every EU country uses the same credit score or scoring model.
Because lending practices vary internationally, it’s more accurate to think about creditworthiness rather than assuming there is a single worldwide credit score.
Frequently Asked Questions
Is there a universal credit score?
No. Every country has its own credit reporting system, scoring models, and lending practices.
Can I use my U.S. credit score in another country?
In most cases, no. Many countries use independent credit reporting systems, so your U.S. credit history may not automatically transfer abroad.
Which country has the highest credit score range?
There isn’t one standard answer. Credit score ranges vary by country and by credit reporting agency. Higher numbers do not necessarily represent better credit compared with another country’s system.
Can I build good credit in any country?
Yes. Although the rules vary, paying bills on time, managing debt responsibly, and reviewing your credit information regularly are positive financial habits in most credit systems.
Final Thoughts
Credit is a global concept, but credit scoring is not.
Someone living in the United States may have a credit score on a 300–850 scale, while someone in India may use a 300–900 system, and someone in Australia may see an entirely different scoring range.
Rather than comparing numbers across countries, focus on what truly matters:
- Pay your bills on time.
- Borrow responsibly.
- Keep your debt manageable.
- Review your credit report regularly.
- Learn how the credit system works where you live.
Healthy financial habits can strengthen your credit profile and improve your access to financial opportunities, whether you’re buying a home, financing a vehicle, starting a business, or planning for the future.
Disclaimer: This article is provided for educational purposes only. Credit reporting laws, scoring models, and lending requirements vary by country, credit bureau, and financial institution. Always consult official consumer protection agencies or financial regulators in your country for the most current information.