
Whether you’re applying for your first credit card, financing a car, renting an apartment, or buying a home, you’ve probably heard the term credit score. But what exactly does it mean, and why does it matter?
Your credit score is one of the most important numbers in your financial life. It can influence whether you’re approved for loans, the interest rates you’re offered, and even how much you’ll pay over time.
The good news? Understanding your credit score isn’t complicated. In this guide, you’ll learn what a credit score is, how it works, what affects it, and practical steps you can take to build and maintain healthy credit.
What Is a Credit Score?
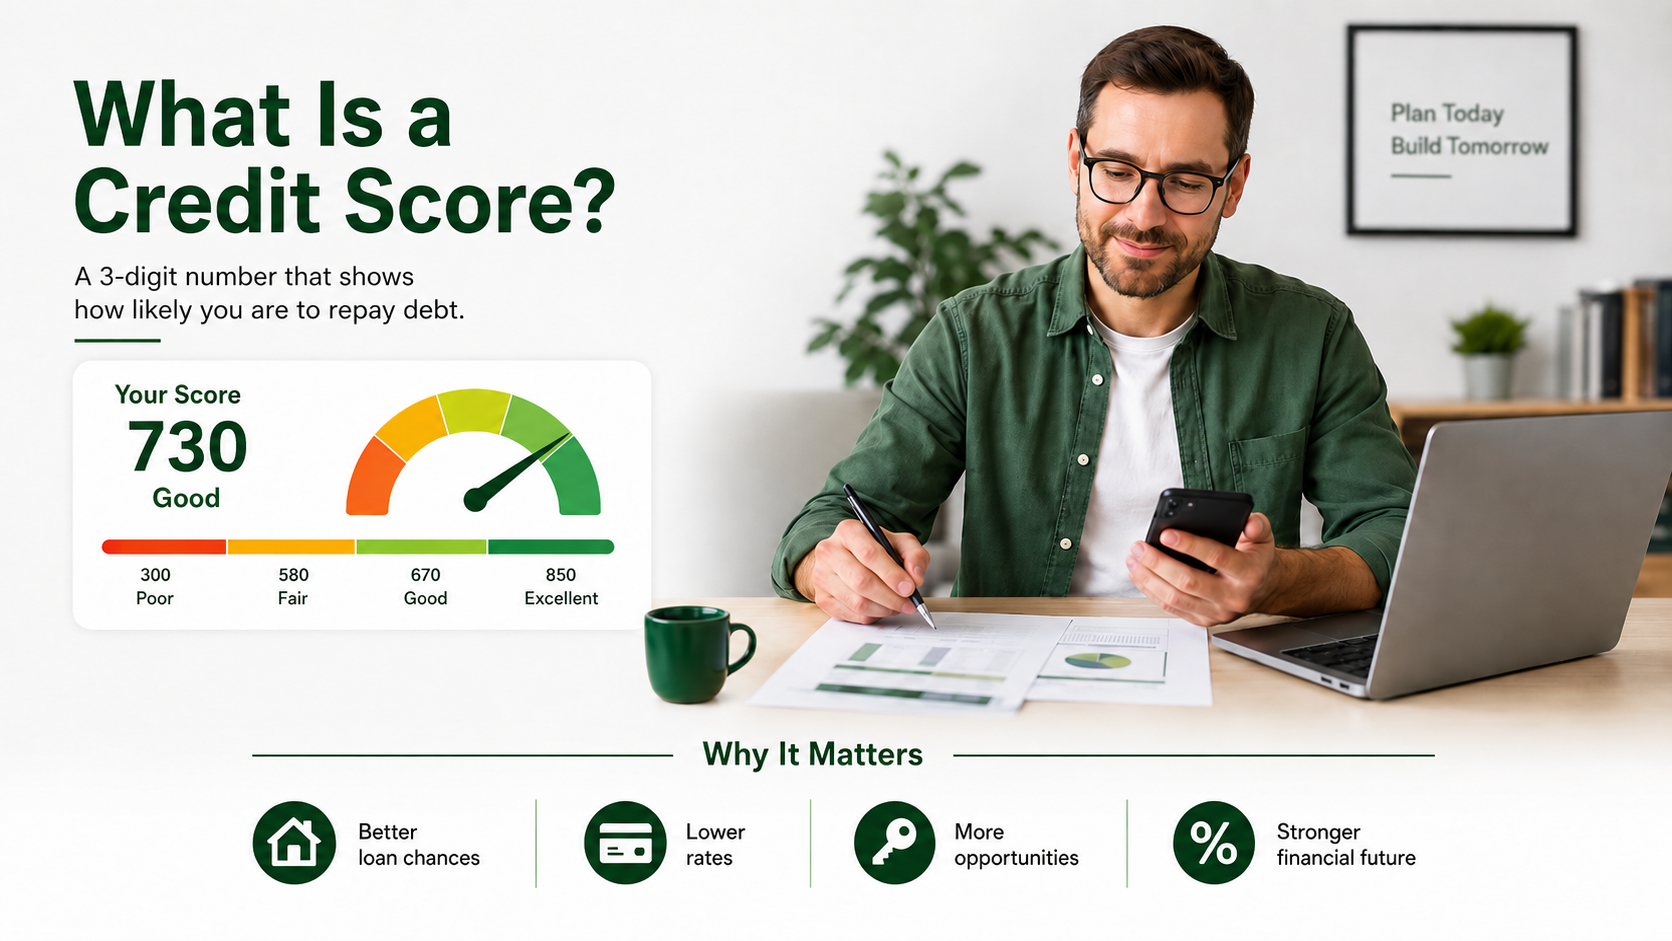
A credit score is a three-digit number that helps lenders estimate how likely you are to repay borrowed money on time. It is calculated using information found in your credit report, including your payment history, outstanding debt, length of credit history, and other credit-related activity.
According to the Consumer Financial Protection Bureau (CFPB), lenders may use credit scores when evaluating applications for:
- Credit cards
- Auto loans
- Mortgages
- Personal loans
- Student loans
- Other credit products
A higher credit score generally indicates lower credit risk, while a lower score may suggest a higher level of risk to lenders.
Important: A credit score does not guarantee loan approval. Lenders may also consider your income, employment history, debt-to-income ratio, assets, and other financial information.
Credit Score vs. Credit Report: What’s the Difference?
Many people use these terms interchangeably, but they are not the same.
| Credit Report | Credit Score |
| A detailed record of your credit history | A numerical summary of your creditworthiness |
| Lists your credit accounts | Usually ranges from 300–850 (depending on the scoring model) |
| Includes payment history, balances, inquiries, and public records (when applicable) | Calculated using information from your credit report |
| Maintained by credit reporting agencies | Generated using credit scoring models |
Think of it this way:
Your credit report is the story. Your credit score is the grade.
What Is Considered a Good Credit Score?
Most commonly used credit scoring models use a range of 300 to 850.
Although scoring models vary, many lenders generally view scores within the following ranges:
| Credit Score | General Rating |
| 300–579 | Poor |
| 580–669 | Fair |
| 670–739 | Good |
| 740–799 | Very Good |
| 800–850 | Excellent |
A higher credit score may improve your chances of qualifying for loans with more favorable interest rates and borrowing terms.
However, every lender sets its own approval requirements, so there is no universal minimum score for every financial product.
Why Does Your Credit Score Matter?
Your credit score can affect many financial decisions throughout your life.
Lenders may use it to determine:
- Whether to approve your loan application
- The interest rate you qualify for
- Your available credit limit
- Loan repayment terms
- Whether additional security or a co-signer is required
In some situations, companies may also review your credit history when evaluating rental applications or other financial agreements, where permitted by law.
Because even a small difference in your interest rate can add up over time, maintaining healthy credit may help reduce the overall cost of borrowing.
Real-Life Example: Why Your Credit Score Matters
Imagine two borrowers applying for the same $30,000 auto loan.
Maria has a credit score of 760. She consistently pays her bills on time, keeps her credit card balances low, and has several years of positive credit history.
John has a credit score of 610. His credit report shows several late payments, and he currently uses a large portion of his available credit.
Both applicants may qualify for financing depending on the lender’s requirements. However, Maria may receive a lower interest rate because her credit history suggests lower lending risk.
John may qualify as well but could receive a higher interest rate, increasing the total amount he pays over the life of the loan.
This example illustrates how maintaining good credit can potentially save thousands of dollars over time.
What Factors Affect Your Credit Score?
While different scoring models use different formulas, several key factors commonly influence your credit score.
1. Payment History
Your payment history is generally considered one of the most important factors.
Making payments on time demonstrates responsible credit management. Late or missed payments may negatively impact your score.
Tip: Setting up automatic payments or payment reminders can help you avoid missing due dates.
2. Credit Utilization (Amounts Owed)
Credit utilization measures how much of your available revolving credit you’re currently using.
For example:
- Credit limit: $5,000
- Current balance: $1,000
Your utilization is 20%.
Many financial experts recommend keeping credit utilization below 30%, with lower percentages generally being more favorable.
3. Length of Credit History
Lenders often prefer seeing a longer history of responsible credit management.
Keeping older accounts open (when appropriate) may help strengthen your overall credit profile.
4. New Credit Applications
Applying for multiple credit accounts within a short period may result in several hard inquiries, which can temporarily affect your credit score.
It’s generally wise to apply for new credit only when necessary.
5. Credit Mix
Responsibly managing different types of credit—such as credit cards, auto loans, mortgages, or student loans—may provide lenders with additional information about how you manage borrowed money.
However, you should never open new accounts solely to improve your credit mix.

How Can You Improve Your Credit Score?
Improving your credit score usually requires consistency rather than quick fixes.
Consider these healthy financial habits:
- Pay all bills on time.
- Keep credit card balances low.
- Avoid applying for unnecessary credit.
- Review your credit reports regularly.
- Dispute inaccurate information promptly.
- Pay down existing debt over time.
- Keep older credit accounts open when appropriate.
- Build responsible credit habits consistently.
Remember that positive changes often take time to appear because your credit score updates as new information is reported to the credit bureaus.
Why Should You Check Your Credit Report?
Your credit report contains the information used to calculate your credit score.
Reviewing it regularly allows you to:
- Verify that your personal information is accurate.
- Identify incorrect account balances.
- Detect fraudulent or unfamiliar accounts.
- Spot reporting errors that could affect your credit score.
- Monitor your financial progress over time.
The Consumer Financial Protection Bureau (CFPB) recommends reviewing your credit reports regularly and disputing any inaccurate information you find.
Frequently Asked Questions
What is the highest possible credit score?
Most commonly used credit scoring models have a maximum score of 850.
How often does a credit score change?
Your credit score can change whenever new information is reported to the credit bureaus, such as payments, new accounts, or updated balances.
Can checking my own credit score lower it?
No. Checking your own credit score is generally considered a soft inquiry and does not affect your score.
Can I have a credit report without a credit score?
Yes. If you have very limited credit history or insufficient recent activity, a credit report may exist without enough information to generate a score.
Final Thoughts
A credit score may be just three digits, but it can have a significant impact on your financial opportunities. It may influence whether you’re approved for loans, the interest rates you receive, and the overall cost of borrowing.
Fortunately, building good credit doesn’t require perfection. Paying bills on time, keeping debt manageable, limiting unnecessary credit applications, and reviewing your credit reports regularly are all positive habits that can contribute to long-term financial health.
Understanding how credit scores work empowers you to make more informed financial decisions, whether you’re applying for your first credit card or preparing to buy your dream home.